France is facing mounting economic and political pressure as rising borrowing costs, ballooning public debt and nationwide protests threaten to narrow the government’s room for additional spending.
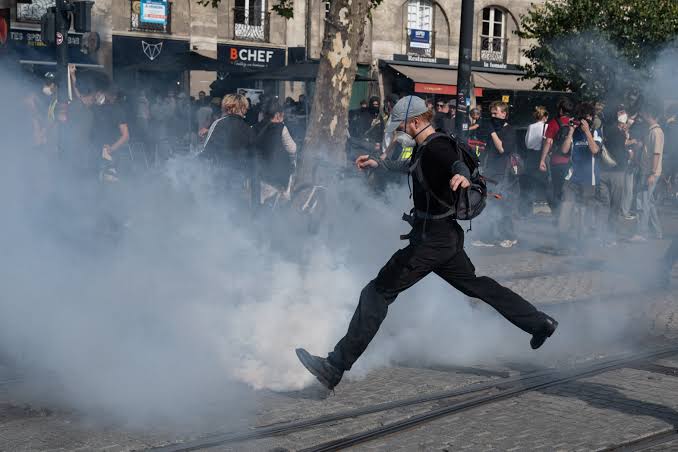
The crisis has intensified following plans to commit €5 billion to education, including €4 billion in low-interest loans for school renovations by 2030 and another €1 billion for universities by 2029. The proposed investment comes amid demonstrations over deteriorating public services, the cost of living and declining employment prospects.
However, with public debt estimated at about 120 per cent of gross domestic product (GDP), questions are mounting over how the government intends to finance the promises without further worsening its already strained public finances.
France’s debt position contrasts sharply with Germany’s, whose debt-to-GDP ratio stands at approximately 65 per cent despite a €600 billion investment package for infrastructure and defence. Germany also retains its AAA credit rating, while France has received lower ratings from major credit agencies, with some assigning it a negative outlook.
The difference has translated into higher borrowing costs for Paris as France currently pays nearly 1.6 percentage points more than Germany on 10-year government bonds, with the risk premium, known as the bond spread, rising to levels last recorded during the 2011 eurozone debt crisis.
Friedrich Heinemann, an economist at the Leibniz Centre for European Economic Research (ZEW) in Mannheim, described the spread as a measure of investors’ confidence in France’s public finances.
He warned that a further increase could raise borrowing costs across the economy, making loans more expensive for households and businesses while putting additional pressure on banks. Such developments, he said, could eventually trigger a wider financial crisis.
France’s debt challenge is not new. The country has consistently spent more than it generates in tax revenue for over five decades, with 1974 marking the last time its national budget was balanced.
The cost of servicing that debt is also accelerating.
France is projected to spend more than €79 billion on interest payments in 2026, rising to over €91 billion in 2027. By 2030, the figure could reach between €125 billion and €132 billion.
The estimates cover the central government, social security funds and local authorities. The central government’s interest bill alone is projected at €62.6 billion, according to Agence France Trésor, the country’s debt management agency.
The pressure is expected to intensify as France refinances existing bonds issued when interest rates were historically low. With substantial budget deficits also requiring fresh borrowing, the government faces the prospect of servicing an increasingly expensive debt portfolio.
Political promises collide with economic realit
Despite the worsening financial outlook, France’s political divisions have made fiscal adjustments increasingly difficult.
Landry Charrier, a researcher at the University of Bonn’s Centre for Advanced Security, Strategic and Integration Studies, argued that public awareness of the country’s debt problem has yet to translate into sufficient support for difficult economic reforms.
He noted that 56 per cent of the French population receive more in government benefits and services than they contribute through taxes and social contributions, according to the national statistics agency, INSEE.
This, he suggested, helps explain why maintaining existing public spending remains attractive to a significant proportion of the population, even as the country’s financial position deteriorates.
Meanwhile, political parties on both the far right and far left continue to advance expensive policy proposals.
Marine Le Pen’s National Rally (RN) has pledged to restore the retirement age to 62 while promising €140 billion in savings. Jean-Luc Mélenchon’s France Unbowed (LFI), on the other hand, has suggested that government bonds held by the French central bank could effectively be written off.
Heinemann criticised such proposals, arguing that political parties were presenting voters with unrealistic solutions that avoid the difficult choices involved in reducing public debt.
He said neither substantial spending cuts nor fiscal consolidation could be avoided indefinitely if France hoped to restore confidence in its public finances.
For France, the challenge is therefore no longer simply how to finance new investments or respond to public protests. It is how to reconcile citizens’ growing demands for government support with the mounting cost of maintaining an increasingly expensive public debt.
France’s debt crisis raises concerns beyond Europe
The country’s predicament is also attracting attention in the United States, where economists are increasingly concerned about the long-term consequences of rising government borrowing.
At a recent event organised by the Bipartisan Policy Center, Heather Long, chief economist at Navy Federal Credit Union, highlighted the differences between the two economies.
She noted that while US public debt is approaching 100 per cent of GDP, France’s is around 120 per cent. The United States also recorded economic growth of slightly above two per cent, compared with approximately 0.5 per cent in France.
Long argued that the US retains greater flexibility to raise revenue and stimulate economic growth, partly because its tax burden on workers is significantly lower.
According to the Organisation for Economic Co-operation and Development (OECD), France’s tax wedge, which measures the difference between employers’ labour costs and employees’ take-home pay, stands at 47.2 per cent. The comparable figure for the United States is 30 per cent.
She warned that France’s experience offers a cautionary example of what could happen when high public debt coincides with weak economic growth, limited revenue-raising capacity and growing generational dissatisfaction.
The protests have also brought the generational dimension of the debt debate into focus, with younger people increasingly concerned about economic opportunities, public services and the financial burden they may inherit.
Phil Swagel, director of the nonpartisan Congressional Budget Office, said governments must confront not only how to reduce deficits but also how the resulting adjustments will be distributed across generations.
He argued that delaying difficult fiscal decisions could leave future generations carrying a disproportionate share of the burden through higher taxes or reduced public spending.