Benin has approved a 100 billion CFA franc ($171 million) Industrial Development Fund aimed at improving access to long-term financing for local manufacturers, supporting factory development and accelerating domestic processing of raw materials.
The government approved the fund at a Cabinet meeting on November 4, alongside the articles of association of the company that will manage it.
The fund will operate through three financing mechanisms. Benin Industrial Invest will provide long-term equity and quasi-equity financing, while the Industrial Guarantee Facility will share lending risks with banks and leasing companies to encourage investment in manufacturing.
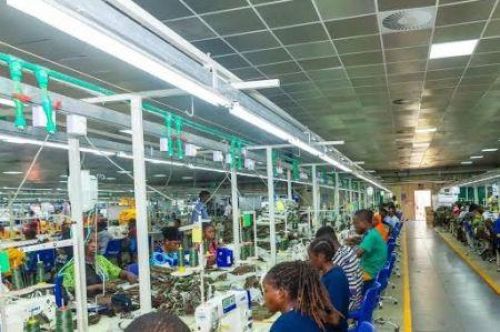
The third component, Ready-to-Use Factories, will support the development of fully equipped industrial facilities across regional development hubs to reduce the cost and time required to establish manufacturing businesses.
The initiative comes amid persistent financing challenges facing businesses in the country.
However, the fund’s impact will depend on how quickly it becomes operational, attracts additional private investment and translates its announced capital into actual financing and industrial development.
According to the African Development Bank, 45 per cent of businesses identified access to finance as their major obstacle in 2024, while long-term loans accounted for less than two per cent of credit extended in 2023.
Manufacturing contributes between eight and 10 per cent of Benin’s Gross Domestic Product, below the Economic Community of West African States’ average of approximately 13 per cent.
The government hopes the fund will strengthen domestic industries, reduce dependence on raw material exports and enable local manufacturers to compete in international markets.
The initiative will complement the Glo-Djigbé Industrial Zone, a major industrial hub focused on processing cotton and other agricultural products. The zone approved 10 projects in 2025, representing planned investments of 76 billion CFA francs and an expected 4,131 jobs.