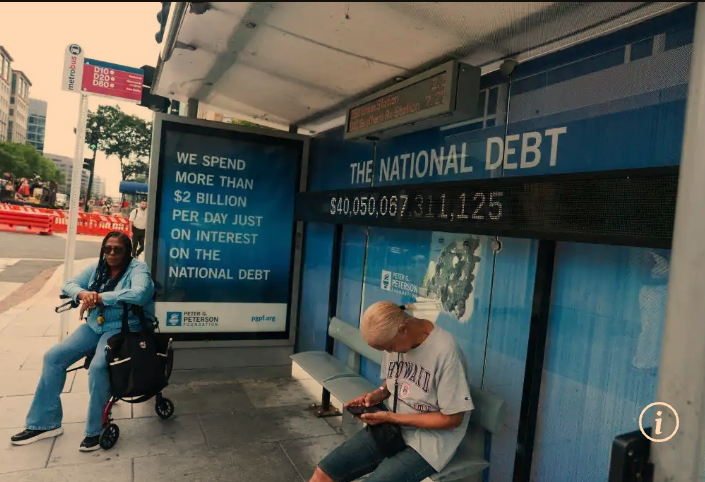
The United States has crossed a fiscal threshold that the world cannot afford to ignore. With US national debt now exceeding $40 trillion, Washington’s claim that economic growth can eventually carry the country out of its debt burden is facing growing scepticism. The central question is no longer simply how large America’s debt has become, but whether the world’s largest economy can continue borrowing at this pace without triggering consequences far beyond its borders.
US Treasury Secretary Scott Bessent has argued that much of the government’s spending is investment in factories, equipment and productive capacity, suggesting that stronger economic growth will eventually make the debt more manageable. That argument has some economic logic: a growing economy can increase government revenues and reduce the relative burden of debt. But growth alone becomes a questionable solution when government spending remains elevated, interest payments continue to rise and tax cuts further constrain public revenue.
The danger is that America could find itself in a cycle in which it borrows more to finance existing obligations, while increasingly expensive debt servicing consumes resources that could otherwise support infrastructure, social programmes and productive investment. If investors begin demanding higher returns to hold US government debt, borrowing costs could rise further, creating an uncomfortable feedback loop.
This is where the $40 trillion figure becomes more than an accounting statistic. The United States occupies a unique position in the global financial system because the dollar remains the world’s dominant reserve currency and US Treasury securities are among the most important assets held by governments, banks and investors worldwide. A serious deterioration in confidence in America’s fiscal position would therefore not remain an American problem.
Higher US bond yields can push up borrowing costs globally, place pressure on emerging-market currencies and make it more expensive for governments and companies outside the United States to raise capital. Countries that hold large quantities of US assets could also face losses if inflation or rising yields erode the real value of those investments.
There is another risk that deserves particular attention: inflation as an indirect escape route from debt. If governments cannot politically raise taxes or reduce spending sufficiently, inflation can gradually reduce the real value of outstanding debt. But such a strategy comes with a price. Persistent inflation erodes household purchasing power, undermines savings and can force investors to demand higher interest rates.
That environment could also challenge the traditional relationship between stocks and bonds. For decades, investors have relied on bonds to provide protection when equities fall. But in a prolonged inflationary period, both stocks and long-term bonds can come under pressure simultaneously. That would have consequences for pension funds, institutional investors and ordinary savers around the world.
The historical comparison with the inflationary era of the 1960s and 1970s is therefore worth considering, although history should not be treated as a prediction. The greater concern is the possibility of a prolonged period in which financial markets deliver positive-looking returns in nominal terms while inflation steadily reduces their real value.
So, is America sitting on a keg of gunpowder? The answer is not that a financial explosion is inevitable. The United States still possesses enormous economic strength, deep capital markets, technological leadership and the extraordinary advantage of issuing the world’s leading reserve currency. These factors give Washington considerably more room to manoeuvre than most countries.
But the fuse is becoming harder to ignore.
The real danger is not necessarily a sudden collapse of the American economy. It could be a slower deterioration: persistently high deficits, rising interest costs, elevated inflation, weaker purchasing power and declining confidence in Washington’s ability to restore fiscal discipline. Such a scenario could produce a prolonged period of economic and financial instability rather than one dramatic crisis.
For the global community, this should be a warning against assuming that America’s fiscal strength is unlimited. Governments, businesses and investors worldwide have built much of the modern financial system around the stability of the US dollar and Treasury market. If that foundation becomes less reliable, the repercussions could reach far beyond Washington and Wall Street.
America therefore needs more than a promise to “grow its way out” of $40 trillion in debt. It needs a credible long-term fiscal strategy that balances investment with spending discipline and ensures that economic growth is not simply used to justify another round of borrowing.
The world’s largest economy cannot borrow indefinitely on the assumption that tomorrow’s growth will always be large enough to pay for today’s spending. The $40 trillion debt milestone should be treated not as a declaration of imminent disaster, but as a serious warning: the longer fiscal imbalances are left unresolved, the greater the risk that the eventual correction will be imposed by financial markets rather than chosen by policymakers.